

Nigeria’s economic growth is projected to accelerate to 4.11 per cent in the fourth quarter from an estimated 3.96 per cent in the third quarter.
The rebound is, however, expected alongside renewed inflationary pressures, fiscal strain, and foreign exchange risks.
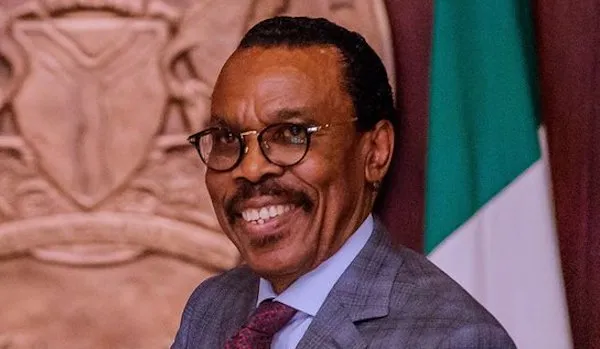
The projection was contained in a macroeconomic review and Q4 2026 outlook presented by Bismarck Rewane at the 22nd Alpha Morgan Economic Review Webinar held on Wednesday.
Rewane said he expects the September monetary policy rate cut by the Central Bank of Nigeria (CBN) to begin to have a stronger effect on economic activity in the final quarter of the year, as the impact of monetary policy typically takes time to filter through the economy.
“Q3’26 growth will be driven more by existing activities due to monetary-policy transmission lag. But it could provide stronger support to economic activity from Q4’26,” the renowned economist said.
Pinnacle Daily reports that the CBN reset its Monetary Policy Rate (MPR), the benchmark rate that influences borrowing costs across the economy, by 350 basis points on September 22, reducing it from 26.5 per cent to 23 per cent.
According to the outlook, the CBN is expected to keep the rate at 23 per cent at its November meeting to assess the effect of the cut on liquidity, inflation and foreign exchange stability.
Lower interest rates are also expected to push Treasury bill yields down further in Q4, potentially encouraging investors to move some funds from fixed-income assets into equities and real assets.
Inflation expected to reverse recent decline
Despite the decline in headline inflation to 15.39 per cent in August 2026, Rewane’s outlook projects a reversal of the recent disinflation trend in the fourth quarter, with inflation expected to rise to 16 per cent in October.
The outlook assigns a 50 per cent probability to inflation accelerating moderately to between 16 per cent and 16.5 per cent. It puts the probability of inflation remaining contained, supported by food supply and foreign exchange stability, at 30 per cent.
There is also a 20 per cent probability that exchange-rate pass-through could push inflation above 17 per cent.
Exchange-rate pass-through refers to the extent to which changes in the naira’s value raise the prices of imported goods and, eventually, domestic products that depend on imported inputs.
The projected inflation pressures are expected to come from faster money supply growth, stronger seasonal demand during the festive period, high fuel and transport costs and food supply conditions.
READ ALSO:
- Dangote Bets $10bn on Power to Drive Africa’s Industrial Growth
- Nigeria’s Economic Stability Improves in Q1, but Rising Costs Threaten Outlook — CPPE
- Risks, Opportunities US-Iran War Poses for Nigeria
- CBN Cuts Rate to 23%: 10 Ways It Will Affect Your Money
The rate cut is expected to support credit creation and private-sector activity, but the increase in liquidity could also add to inflationary pressure if money and credit grow faster than the economy’s capacity to produce goods and services.
Naira seen stable as reserves support FX market
The outlook projects relative stability for the official naira exchange rate in Q4, with the Nigerian Foreign Exchange Market rate expected to trade between ₦1,300 and ₦1,410 to the dollar.
The parallel market, however, is expected to face mild depreciation pressure, with the rate potentially weakening to between ₦1,390 and ₦1,400 to the dollar.
Nigeria’s gross external reserves, which the outlook puts at an 18-year high of between $53.3 billion and $54.7 billion, are expected to remain well funded by sustained oil earnings and foreign portfolio investment inflows.
But Rewane warned that the reduction in domestic interest rates could create additional foreign exchange and capital-flow risks as Nigeria’s interest-rate position diverges from major global economies.
“Nigeria is moving against the global monetary tide. The divergence could heighten FX and capital-flow risks,” he said.
The concern is that lower Nigerian interest rates relative to rates in major economies could reduce the incentive for some foreign investors to hold naira-denominated assets, potentially putting pressure on the currency and capital flows.
Banks, manufacturers to feel rate cut
The lower benchmark interest rate is expected to have different effects across major sectors of the economy.
For banks, cheaper borrowing costs are expected to increase demand for loans and support private-sector credit growth. However, lower market yields could also put pressure on banks’ net interest margins, which measure the difference between what banks earn on loans and investments and what they pay to fund those assets.
“Banks could see stronger credit demand, while the effect on margins will depend on how quickly lending and deposit rates reprice,” Rewane said.
Cheaper loans could also reduce the pressure on borrowers to service existing debt, potentially lowering loan defaults and the amount banks need to set aside for bad loans.
Real estate and construction are also expected to benefit as financing becomes cheaper. The outlook projects stronger activity in residential and commercial property, although existing high mortgage rates could delay the full impact until banks adjust their lending rates.
Lower borrowing costs are also expected to support infrastructure projects and increase demand for cement and other building materials.
Capital-intensive manufacturers with significant borrowing could benefit from lower commercial paper and bank-loan rates, reducing their debt-servicing costs.
Consumer goods and manufacturing companies are similarly expected to benefit from lower short-term borrowing costs, which could release funds for inventories and production. The usual increase in consumer spending during the festive season is expected to reinforce the effect.
Telecommunications and ICT companies could benefit from lower interest expenses on local debt and moderating lease obligations, while demand for data and other digital services remains sustained.
Oil sector remains tied to global prices
The oil and gas sector is expected to be less directly affected by the domestic rate cut because its performance is more closely linked to global crude prices, production volumes and upstream investment.
The outlook projects Brent crude prices at between $95 and $105 per barrel in Q4, a range expected to support Nigeria’s external trade position.
The sector’s operating costs and major capital debt structures are largely denominated in US dollars, which provides some insulation from changes in domestic interest rates.
However, oil revenues remain exposed to OPEC+ production decisions, global demand and geopolitical developments, including Iran-US tensions. A sharp fall in crude prices could reduce foreign exchange earnings and slow the accumulation of reserves.
Fiscal deficit and debt remain major pressure points
Despite the projected improvement in growth, Nigeria’s fiscal position is expected to remain under pressure.
The fiscal deficit, representing the gap between government revenue and expenditure, is projected to widen to 4.2 per cent of GDP in 2026. Total public debt is also projected to reach ₦188.48 trillion, equivalent to 38.3 per cent of GDP.
The outlook attributes the fiscal pressure to high debt-servicing costs, spending leakages and structural weaknesses in government revenue.
Election-related spending is also identified as a domestic risk because increased government disbursements could raise demand in the economy while adding to existing fiscal deficits and debt-servicing pressures.

Alex is a business journalist cum data enthusiast with the Pinnacle Daily. He can be reached via ealex@thepinnacleng.com, @ehime_alex on X