

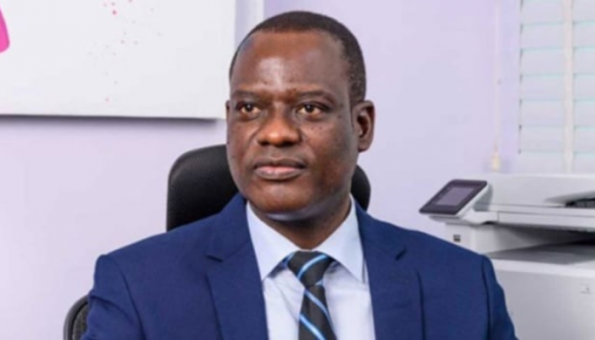
The Federal Government has proposed requiring major economic policy changes to undergo an impact assessment before implementation to reduce policy uncertainty, improve investor confidence, and create a more predictable business environment.
The proposal is contained in the Nigeria Economic Policy Framework presented by Taiwo Oyedele, Minister of Finance and Coordinating Minister of the Economy, at the opening of the 32nd Nigerian Economic Summit.
The framework proposes a Policy Impact Statement, which would require government to explain the problem a proposed intervention seeks to solve, the evidence supporting it, who would benefit, who would bear the cost and the conditions under which the policy would end.
The proposed requirement would cover major economic interventions, including tax adjustments, tariff changes, regulatory restrictions,s and incentives.
Presenting the framework, Oyedele said frequent policy changes, weak impact assessments and inadequate consultation had made it difficult for businesses to plan and investors to commit capital.
“Policy uncertainty is an invisible tax on enterprise. And unlike most taxes, it generates no revenue for government—it only destroys value and discourages investment,” he said.
He argued that Nigeria’s challenge was not a lack of economic plans but the failure to maintain a consistent policy direction and implement reforms in a disciplined manner.
According to him, policies introduced by one administration are often undermined by subsequent decisions, leaving the country without an enduring economic philosophy.
The framework seeks to establish common principles for economic policymaking that would remain in place beyond individual administrations and electoral cycles.
Oyedele said the document was not a development plan, a list of capital projects or an administration’s manifesto, but a proposed national economic doctrine setting out how economic decisions should be made and how progress should be measured.
READ ALSO:
- FG: IMF Report Confirms Tinubu Reforms Are Working
- Banks’ Recapitalisation Wins Mean Little Without Business Lending, CPPE Warns
- FSI, NCC Train 95 Female Students, Select 15 for Tech Internships
- NGX’s ₦912m Other Income Leaves Penalties Unclear
- 80% of First HoldCo’s Cash Locked in CRR as Lending Slows
The framework is intended to support a productive, competitive, diversified and inclusive economy that creates quality jobs, raises household incomes and delivers shared prosperity.
Oyedele said economic performance should not be assessed through aggregate figures alone, arguing that improvements must also be reflected in employment, household earnings, agricultural productivity and the ability of businesses to expand.
“GDP growth matters, but per capita income matters more,” he said.
Gross domestic product (GDP) measures the total value of goods and services produced in an economy, while per capita income measures average income per person. The framework argues that economic progress should be assessed partly by whether growth translates into improved living standards.
The proposed framework organises its priorities around seven interconnected systems: stability, productivity, enterprise, capital, people, markets and institutions.
It identifies three core principles for policymaking: enterprise as the engine of growth, open but fair markets, and coordination across government institutions.
Under the enterprise principle, the private sector would drive production and employment, while government would provide public services, uphold the rule of law, address genuine market failures and protect vulnerable groups.
On market competition, Oyedele said government could support local industries through industrial policy but should avoid protecting inefficient businesses indefinitely.
“A tariff must serve as a runway for local industry to take off—never a permanent shelter from competition,” he said.
Tariffs are taxes imposed on imported goods. They can make imported products more expensive and give local producers room to compete, but prolonged protection can also shield inefficient businesses from competition.
The framework also calls for closer coordination among ministries, departments and agencies to reduce the combined cost of government regulations and administrative requirements on businesses.
To strengthen accountability, it proposes an annual National Economic Scorecard to be published on or before Independence Day.
The scorecard would provide a public assessment of whether real wages are rising, productive jobs are increasing, and poverty is declining.
Real wages measure workers’ earnings after accounting for changes in prices. The measure helps show whether people can afford more goods and services with their income.
Oyedele said the proposed scorecard would make it harder for government to overlook economic outcomes that affect households and businesses.
The framework is currently a consultation draft and has not been approved as government policy.
Oyedele said it was being presented first to the Nigerian Economic Summit Group (NESG) to encourage consultation with businesses and other stakeholders and build national consensus on the country’s economic direction.
The public consultation will run until November 27, 2026, with contributions invited through seventeen core questions.
Following validation, the framework will proceed to the Federal Executive Council for approval and the National Economic Council for endorsement.
Oyedele urged the NESG and private-sector stakeholders to scrutinise the proposals and contribute to developing a lasting national economic framework.
He added that the objective was to replace frequent policy changes and inconsistent decision-making with a predictable approach that could support investment, business expansion and long-term economic growth.

Alex is a business journalist cum data enthusiast with the Pinnacle Daily. He can be reached via ealex@thepinnacleng.com, @ehime_alex on X